Contractor payments / 2026 tax year
1099-NEC Threshold for 2026: $600 or $2,000?
For payments made in 2026, the usual federal 1099-NEC threshold for nonemployee compensation is $2,000 per payee. The earlier $600 rule applies to 2025 payments. Start with the payment year, then review the recipient, service, payment method and any exceptions.
Check the IRS payment-year guidanceXLSX and CSV · No signup required · Manual review, with no account connection
Updated IRS sources checked
Use the payment year, not the year you submit the form
A search for “1099 in 2026” can mean two different things. A return submitted in early 2026 commonly reports 2025 payments. Payments made during 2026 are generally reported in early 2027. Those are different reporting periods.
| Payment period | Usual federal NEC threshold | Usual submission year |
|---|---|---|
| January–December 2025 | $600 per payee | 2026 |
| January–December 2026 | $2,000 per payee | 2027 |
These are the usual federal nonemployee-compensation thresholds. They are not a rule for every 1099 form or payment type. If backup withholding occurred, reporting can be required regardless of amount. State obligations may differ, and later payment years require the applicable inflation-adjusted guidance.
Sources: IRS reporting thresholds and Publication 1099.
Why your contractor's bills and 1099 total can differ
Suppose a small business has $3,600 of service bills from one U.S. sole-proprietor contractor. The business checks the W-9 and reviews each payment. This fictional example assumes ordinary reportable business services, no backup withholding, no refunds, and no other exceptions.
| Record | Amount (USD) | Review result |
|---|---|---|
| ACH payment made in 2026 | $1,800 | Included in this example's NEC payment total |
| Check payment made in 2026 | $500 | Included in this example's NEC payment total |
| Credit-card payment made in 2026 | $900 | Excluded from the payer's NEC total under the payment-card reporting rules |
| Bill still unpaid at year-end | $400 | Not a payment made in 2026 |
| Reviewed NEC payment total | $2,300 | $1,800 + $500; the usual $2,000 federal threshold is met in this example |
The business paid $3,200, but the reviewed NEC amount is $2,300. The unpaid $400 explains the gap between bills and payments; the $900 card payment explains the gap between payments and the NEC total. Keep those explanations with the source records.
Payment-card transactions and qualifying third-party-network transactions covered by 1099-K rules are not also reported by the business on 1099-NEC. Check the underlying transaction: using a payment app does not, by itself, establish an exclusion.
Source: IRS 1099-MISC and 1099-NEC instructions, Form 1099-K and nonemployee-compensation sections.
A payment checklist you can use before handoff
The Excel workbook includes these ten checks with editable status and notes, plus a blank 50-row Payment review log. Record the date, payee, reference, amount, method and review decision for each entry. The CSV contains the checklist only.
Amounts and decisions are entered manually. The files do not calculate filing eligibility or totals, convert currencies, connect to Bokeping, or submit a tax return. Keep full SSNs and EINs in your secure source records, not in this working checklist.
01Choose the payment year
Use January 1–December 31, 2026 payment records. Check actual payment dates, not just bill dates or your company's fiscal year.
02Check contractor information
Compare the legal name, address, tax classification and securely stored Tax ID with the W-9. Record its status here, not a full SSN or EIN.
03Review the recipient and service
Confirm the recipient and payment type with your preparer. A vendor checkbox alone does not decide worker classification or tax treatment.
04Gather actual payments
Trace bills, expenses and payments to references and bank records. Record each payment once, including installments made during the year.
05Separate unpaid bills
Keep unpaid balances out of the paid total. A vendor's purchase total or open balance is not the amount paid during the year.
06Review card and network payments
Identify payments covered by Form 1099-K rules. Do not classify every payment app or bank transfer as excluded without checking the transaction.
07Investigate refunds and corrections
Keep original payment references with refunds, voids and adjustments. Ask your preparer how each affects the amount being reported.
08Review each payee separately
Compare reviewed payments to the 2026 federal $2,000 threshold per payee. Check backup withholding, special cases and state requirements separately.
09Explain differences in the report
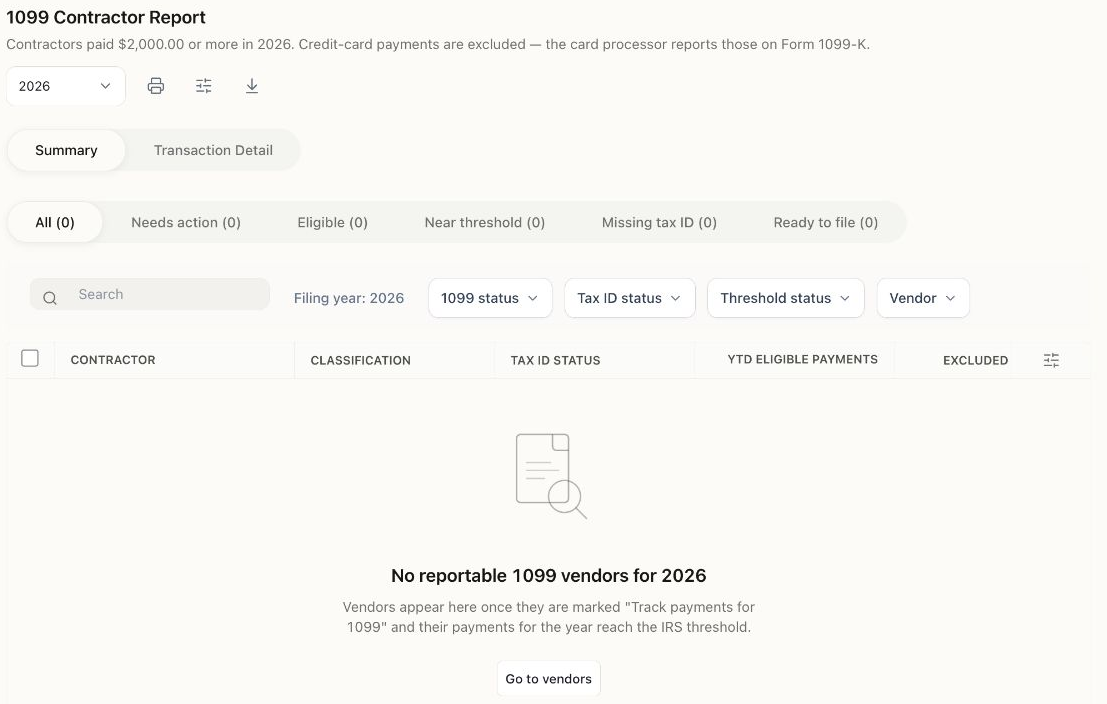
Check the selected year, contractor flag, filters and exclusions. Bokeping's summary can omit below-threshold vendors; an empty list is not proof of completeness.
10Review the export and handoff
Check the full-year export, resolve open questions and send records securely to your preparer. Keep filing and recipient-delivery confirmation separately.
Use Form W-9 to obtain the payee information your preparer needs. Completion of a checklist does not replace reviewing the applicable reporting rules.
Review the records in Bokeping
Start in Contacts → Vendors, then open Reports → 1099 Contractor Report. The current report supports companies whose base currency is USD. It uses the selected calendar year; it is not a company fiscal-year report.
Check the vendor record
Review Track Payments for 1099, the contractor/form classification and W-9 information. A saved “Verified” status can reflect the information held in Bokeping; it does not establish an IRS TIN-match result.
Select the calendar year and inspect Summary
For 2026, the report displays the $2,000 threshold. Review amounts by contractor, clear filters when someone seems missing, and compare with the complete payment history. The summary can omit below-threshold contractors.
Trace differences in Transaction Detail
Check payment dates, references, accounts and amounts. Review rows marked “Excluded — 1099-K” against the actual payment method. Investigate differences rather than changing a classification just to match a purchase total.
Check the export before sharing
The export controls produce the full-year summary; the current on-screen tab and filters do not narrow that export. Check the selected year and output before sending it securely to your preparer. Exporting does not file with the IRS or deliver the recipient copy.
Keep the review connected to the source records
Use Bokeping to organize vendor records and trace payments. Use your preparer or filing service for the filing decision, submission and recipient delivery.
Organize contractor records in BokepingFAQs
1099-NEC questions
For payments made during calendar year 2026, the usual federal nonemployee-compensation reporting threshold is $2,000 per payee. The usual threshold for 2025 payments was $600, even when the return was submitted in 2026. Backup withholding and other exceptions can require reporting below the usual threshold; review the IRS instructions and applicable state rules.
No. A payer's information-reporting threshold does not make the recipient's income tax-free. This page is a record-preparation guide for businesses making payments; it does not determine the contractor's tax liability.
Payments covered by Form 1099-K rules, including payment-card transactions and qualifying third-party-network transactions, are not also reported by the business on Form 1099-NEC. Review the actual payment method and supporting records. The name of an app alone does not establish the treatment.
The Excel workbook and checklist CSV are free to download without signing up. The workbook has a Checklist sheet and a blank Payment review log with 50 rows. You enter and review the records manually. It does not calculate filing eligibility, sync with Bokeping, import transactions, or submit a return.
No. Bokeping helps you review contractor records, annual totals and transaction details, and export the report. A downloaded report, W-9 status or Ready to file label does not mean a return has been accepted by the IRS or delivered to the contractor. Filing and recipient delivery are separate steps.
IRS sources and scope
Sources checked on . This guide addresses preparation of U.S. contractor payment records for the 2026 federal NEC rules. Review special cases and state requirements with the person preparing your returns.
- IRS: Am I required to file a Form 1099 or other information return?
Payment-year thresholds and backup-withholding exceptions.
- IRS: Instructions for Forms 1099-MISC and 1099-NEC
Reportable services, recipient rules, and payment-card and third-party-network exclusions.
- IRS: About Form W-9
Obtaining a payee's taxpayer identification number and certification.
- IRS: Publication 1099 (2026)
General filing, recipient statements, and current-year reporting instructions.